Illinois dealer demonstrates sub-$500 SUV financing requires 72-month term and perfect borrowing profile.
A Chevrolet dealer in Illinois claims he can deliver a 2026 Trax SUV for $490 monthly with zero down payment. The math works. Credit requirements tell a different story.
The financing structure reflects broader industry shifts toward extended loan terms as vehicle affordability pressures mount. Buy From Mike dealership owner Mike Pirozz posted the breakdown on TikTok in May 2024, showing how dealers navigate payment-focused sales conversations while interest rates reshape borrowing costs across the retail automotive sector.
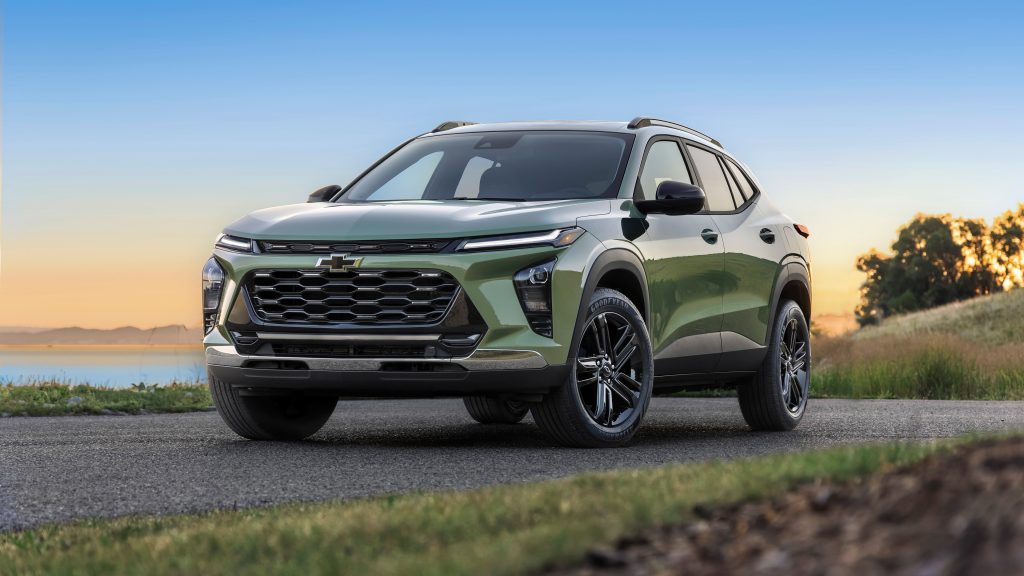
Payment Mathematics Require Perfect Alignment
Pirozz's calculation centers on specific numbers that must align precisely. The 2026 Trax LS carries a $23,000 discounted price, rising to $25,732 after taxes and fees. Financing the full amount at 5.49% interest across 72 months produces the $490 payment. The total cost reaches $35,280 over six years—$9,548 in interest charges alone. Change any variable and the formula breaks. A 60-month term pushes payments above $500. Extended financing terms have become standard tools for maintaining affordability as vehicle prices climb. Credit scores below 750 typically face rates between 7% and 12%, destroying the payment target immediately.
Social Media Response Questions Credit Reality
TikTok viewers immediately challenged the deal's accessibility. "Credit was perfect," one commenter wrote, highlighting the gap between advertised rates and typical borrower experiences. Another calculated the total cost: "Over 54k for that?" referring to principal plus interest. Pirozz responded to payment duration questions with a simple "72 mo," confirming the extended term. The video attracted over 5,000 views within weeks of posting. Comments revealed familiar brand divisions, with one user writing "Yeah but it's a Chevy" while another countered "Still better then a ford." The exchange demonstrates how payment-focused marketing intersects with brand loyalty and borrower qualification realities.
Rate Spread Separates Qualified From Marginal Buyers
The 5.49% rate assumes exceptional credit profiles that many buyers lack. Average new car rates reached 7.1% in early 2024, according to Edmunds data, while subprime borrowers face double-digit costs. A buyer with fair credit paying 9% interest would see the same Trax payment jump to $567 monthly—$77 above Pirozz's target. The difference compounds over 72 months, adding $5,544 to total costs. Premium pricing pressures have made rate sensitivity acute across all segments. Dealers increasingly present best-case scenarios while actual qualification rates vary dramatically by credit tier and regional lending conditions.
Extended Terms Reshape Ownership Cycles
The 72-month financing term exceeds typical vehicle ownership patterns, creating underwater equity positions for early sellers. Trade-in values typically depreciate faster than loan balances during the first three years. Buyers choosing six-year terms often owe more than their vehicle's worth until month 48 or beyond. Pirozz strips additional coverage options—extended warranties and GAP insurance—that could protect against negative equity scenarios. The base LS trim lacks many features buyers expect, potentially driving upgrade desires before loan completion. General Motors' portfolio strategy increasingly relies on entry-level pricing to capture payment-sensitive customers while pushing profit margins through higher trims and financing products.
Pirozz operates from Melrose, Illinois, serving Chicago-area buyers where vehicle affordability challenges mirror national trends. His TikTok account focuses on payment-centric sales approaches that have become standard across U.S. dealerships. Average new vehicle loan terms reached 69.3 months in 2024. The complete Chevrolet model history and specifications are catalogued in the Global Auto Index manufacturer database.
