How major automakers are repositioning their product portfolios through electrification, market exits, and technology pivots amid industry restructuring.
Overview
The automotive industry's strategic realignment accelerated through April 2026, with manufacturers making decisive moves across electrification, market positioning, and technology adoption. Electric vehicle transitions dominated product planning, as Nissan committed to electric-only powertrains for the Juke while Mercedes-EQS received enhanced battery architecture. Market segmentation strategies emerged clearly, with luxury brands like Rolls-Royce pursuing ultra-exclusive models and Chevrolet repositioning performance variants to capture broader market share. Geographic market exits became more common, exemplified by Nissan's decision to withdraw the Skyline from US markets while maintaining global presence. Autonomous driving technology faced industry-wide recalibration, with BMW and Mercedes-Benz stepping back from Level-3 systems after initial deployments. Infrastructure challenges persisted in EV charging networks, while warranty disputes highlighted ongoing quality control issues across multiple brands. These developments reflect broader industry consolidation pressures and the need for clearer strategic focus as traditional automotive business models face disruption.
Key Entities
| Entity | Type | Coverage |
|---|---|---|
| Mercedes-EQS | model | Battery and architecture upgrades for 2027 |
| Nissan | brand | Multiple model updates including Xterra return, Skyline changes, Juke electrification |
| BMW | brand | Level-3 autonomy strategy reversal |
| Mercedes-Benz | brand | Autonomous driving technology retreat and EQS updates |
| Rolls-Royce | brand | Ultra-luxury Project Nightingale limited production |
| Chevrolet | brand | Grand Sport performance model pricing strategy |
| Hyundai | brand | Ioniq 5 charging infrastructure and dealer issues |
| Aston Martin | brand | Single-seat prototype development with F1 technology |
| Kia | brand | US truck market expansion plans through 2034 |
Analysis
The April 2026 automotive landscape reveals three fundamental shifts reshaping how manufacturers approach product development and market positioning. First, electrification strategies have moved beyond experimental phases into concrete product commitments, with clear differentiation between brands pursuing full electric transitions versus those maintaining hybrid approaches. Nissan's electric-only Juke represents this binary choice, while Mercedes' battery architecture upgrades show how premium brands are investing in technical superiority rather than market breadth. Second, geographic market rationalization has accelerated as manufacturers optimize their global footprints. Nissan's US market exit for the Skyline signals how brands are prioritizing profitable regions over universal presence, a trend likely to expand as regulatory divergence increases costs of maintaining global product lines. This geographic selectivity extends beyond individual models to entire market strategies, reflecting more disciplined capital allocation in an industry facing margin pressure. Third, technology adoption timelines are being recalibrated based on real-world deployment experiences rather than theoretical capabilities. The BMW and Mercedes retreat from Level-3 autonomy demonstrates how industry leaders are adjusting expectations after encountering practical implementation challenges. This measured approach suggests future technology rollouts will follow more conservative timelines, with manufacturers prioritizing reliability over first-mover advantages. Product positioning strategies reveal increasing market segmentation, with luxury brands pursuing ultra-premium segments while mainstream manufacturers focus on value positioning. Rolls-Royce's Project Nightingale exemplifies the luxury sector's move toward extreme exclusivity, while Chevrolet's Grand Sport pricing strategy shows mass-market brands competing on performance value. These positioning choices reflect broader industry consolidation, where clear brand differentiation becomes essential for survival. Infrastructure development continues to lag behind EV adoption plans, creating market friction visible in charging speed discrepancies and dealer communication issues. This infrastructure gap represents both a constraint on EV growth and an opportunity for manufacturers willing to invest in charging networks or dealer training. Quality control challenges persist across price segments, from warranty disputes on mainstream vehicles to charging infrastructure reliability issues, indicating that rapid product development cycles may be compromising traditional automotive reliability standards.
Timeline
- 2026-04 — Aston Martin tests single-seat prototype with Formula 1 halo
- 2026-04 — Kia targets 90,000 US truck sales by 2034 with body-on-frame pickup
- 2026-04 — Ioniq 5 charges 240kW but Hyundai dealers oversell speed claims
- 2026-04 — BMW and Mercedes-Benz abandon Level-3 autonomy after rollouts
- 2026-04 — Chevrolet Grand Sport starts $88,495, undercutting Z06 by $32,000
- 2026-04 — Mercedes EQS gets 122kWh battery and 800V architecture for 2027
- 2026-04 — Nissan Xterra returns 2028 with naturally aspirated V6
- 2026-04 — Nissan teases Skyline return with 450hp but drops US market
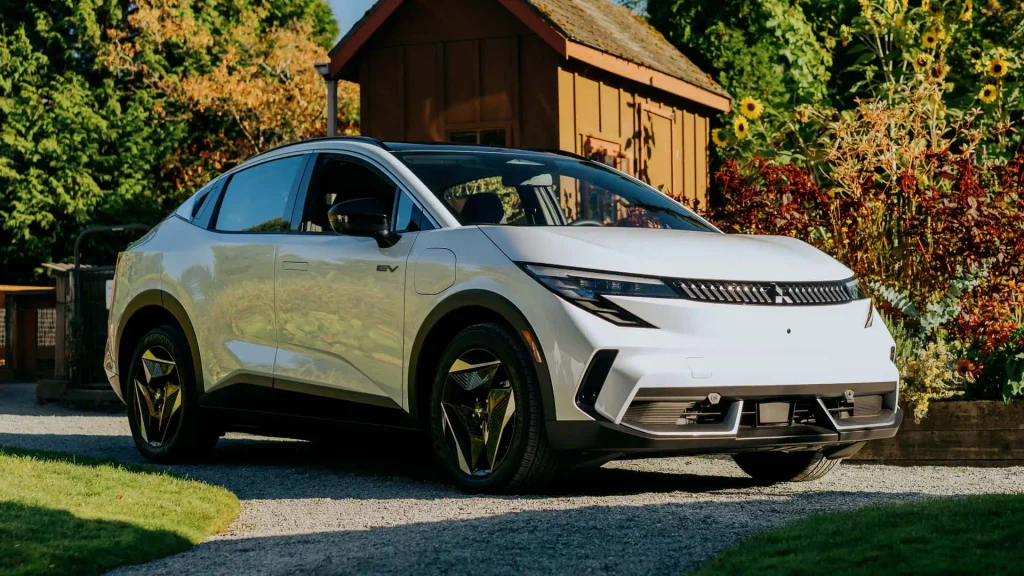
- 2026-04 — Nissan Juke 2027 debuts electric-only with angular design
- 2026-04 — Arizona mechanic refuses $11,000 repair, sends Sierra to warranty
- 2026-04 — Rolls-Royce Project Nightingale caps 100 units at $1m-plus
- 2026-04 — Yuma mechanic refuses $11,000 repair on warranty GMC Denali
All Articles (12)
- Mercedes EQS gets 122kWh battery and 800V architecture for 2027 — 2026-04-14
- Nissan Xterra returns 2028 with naturally aspirated V6 — 2026-04-14
- Nissan teases Skyline return with 450hp but drops US market — 2026-04-14
- Nissan Juke 2027 debuts electric-only with angular design — 2026-04-14
- Arizona mechanic refuses $11,000 repair, sends Sierra to warranty — 2026-04-14
- Rolls-Royce Project Nightingale caps 100 units at $1m-plus — 2026-04-14
- Yuma mechanic refuses $11,000 repair on warranty GMC Denali — 2026-04-14
- BMW and Mercedes-Benz abandon Level-3 autonomy after rollouts — 2026-04-13
- Chevrolet Grand Sport starts $88,495, undercutting Z06 by $32,000 — 2026-04-13
- Ioniq 5 charges 240kW but Hyundai dealers oversell speed claims — 2026-04-12
- Aston Martin tests single-seat prototype with Formula 1 halo — 2026-04-09
- Kia targets 90,000 US truck sales by 2034 with body-on-frame pickup — 2026-04-09